Register
 Login
 Register




Rising Treasury yields hit stocks and gold
Jamie Dutta >
Market Analyst
Jamie Dutta >
Market Analyst
 Updated Thu, 2024 May 30 01:22
Headlines
* 10-year Treasury yield tops 4.6% for the first time in nearly a month
* Yen hits 4-week low, euro dips after German inflation data
* Gold slips on higher dollar and bond yields
* Stock indices decline as little outside of Nvidia seems to be working
FX: USD advanced north, closing just above the 50-day SMA at 105.05 and last week’s highs. Stronger Treasury yields supported the move with a lack of news flow and Fed speak. Eyes are on the second estimate of US GDP ahead of Friday’s inflation data.
EUR fell quite sharply and settled on its lows. This came after the bearish candlestick on Tuesday. There is a zone of support just below 1.08. This includes the midway point of the Q4 rally, the 200-day and 50-day SMAs. German CPI printed marginally hotter than forecast though the m/m number was softer. EZ CPI is published on Friday.
GBP fell back and closed on its lows at 1.27. There was little news, just strong dollar buying on the rising Treasury yield theme. There are now only around 31 bps of BoE rate cuts priced in for this year.
USD/JPY broke higher as we predicted yesterday and is pushing towards 158. Interesting that USD/CNY is drifting towards the highs of the year and strong resistance. There is speculation that Chinese authorities do favour a weaker currency. That would be good for USD and bad for risky assets.
AUD turned lower even after stronger than expected CPI. That curbed any chances of a rate cut by the RBA this year. But the CNY story above probably has a lot to do with why the aussie wasn’t better bid. USD/CAD jumped up above 1.37 and through its 50-day SMA at 1.3659. Risk sentiment hit all the cyclical, commod$ currencies.
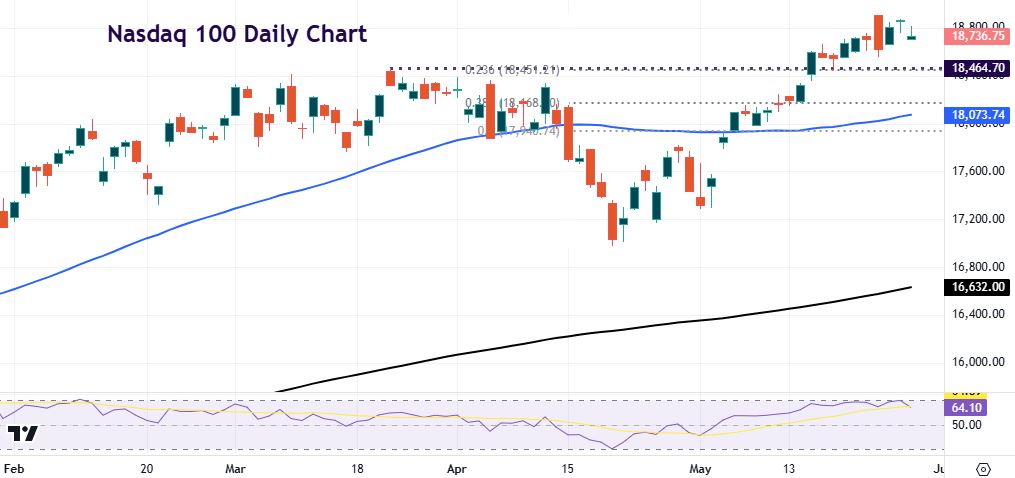
US Stocks: Indices closed down for a second straight day. Higher yields were again the headwind for stocks, as we mentioned in our weekly Monday webinar. The S&P 500 finished lower by 0.74% at 5,267. The Nasdaq 100 settled 0.70% down at 18,737. The Dow underperformed, closing in the red by 1.06% at 38,442. Energy, industrials and materials were the main losers with no sector in the green and tech the strongest, but still showing losses of 0.36%.
Asian Stocks: APAC futures are lower. Asian stocks were also mostly negative with a subdued Wall Street. The ASX 200 was hit by stronger CPI data and the jump in yields. The Nikkei 225 struggled again at 39,000 with strong yields the headwind. China stocks were mixed with the mainland outperforming this time, on property support measures.
Gold got hit and will be looking to last week’s low at $2325/27 as support. Rising bond yields and hotter CPI, from Europe to Australia, is not favouring gold bugs.
Day Ahead – Second tier data
It might be the calm before the storm as there is little on the calendar to excite markets on Thursday. But this comes ahead of “CPI Friday” with inflation reports from Tokyo, the eurozone and the US. FX volatility is relatively low at present, so too the VIX, Wall Street’s fear gauge, that measures volatility on the S&P 500. There is more Fedspeak which continues ahead of the blackout period starting this weekend, before the FOMC meeting on 12 June.
The chances of even less Fed easing are a possibility with around 30bp of cuts still priced in by markets. That said, a cooler PCE report on Friday could upset these odds. We do get the second estimate of US GDP, with a small revision anticipated. The April eurozone unemployment rate is also released, which has been holding steady at a historic low at 6.5%. The tight labour market and still strong wage growth is a concern for the ECB.
Chart of the Day – Nasdaq relatively strong
AI-related news continues to help tech stocks and especially the current market darling, Nvidia. It still made a new record high yesterday as it nears Apple’s market cap. There is now (just!) $100 billion between the two megacaps at $2.8 and $2.9 trillion. Nvidia’s shares have surged 13% since last week’s results and above estimate revenue plus a stock split. The stock has more than doubled this year after more than tripling in 2023. In contrast, Apple is down around 2% this year as struggles with competition in China and weak iPhone demand keep buyers at bay. The biggest company by market cap remains Microsoft, which is around $3.1 trillion.
For the indices, the tech-dominated Nasdaq, up 8.6% this month, has strongly outperformed the Dow. Current rotations from more defensive sectors seem to be driven by AI exuberance more than macro and micro factors, like stronger yields. Add to this the ongoing meme stock frenzy and you can see where we are coming from. The record high remains in reach at 18,907 with strong support around 18,464.70.
Disclaimer: The material provided here has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. Whilst it is not subject to any prohibition on dealing ahead of the dissemination of investment research we will not seek to take any advantage before providing it to our client. No representation or warranty is given as to the accuracy or completeness of this information and therefore it shouldn’t be relied upon as such. Any research provided does not have regard to specific financial situations, needs or investment objectives. Vantage accepts no responsibility for any use that may be made of these comments and for any consequences that result. Consequently, any person acting on it does so entirely at their own risk. We advise any readers of this material to seek professional advice where necessary. Without the approval of Vantage, reproduction or redistribution of this information isn’t permitted.
-
Open Trading Account
Discover the endless trading possibilities with our cutting-edge platform, designed to empower our traders. Practice trading the markets with a free demo account today.
-
Download Vantage App
Trade on the go with the Vantage All-In-One Trading App, where smooth execution and market access come together in the palm of your hand.
-
Start Trading
Are you an existing user? Login to your account to start trading 1,000+ CFD products including forex, indices, gold, shares and more.