Register
 Login
 Register




Geopolitical tensions simmer as stocks are choppy
Jamie Dutta >
Market Analyst
Jamie Dutta >
Market Analyst
 Updated Wed, 2024 November 20 02:00
* Ukraine’s use of western rockets may prompt nuclear response says Russia
* Trump to pick Howard Lutnick as commerce secretary
* Traders trim big Bank of Canada rate cut bets after inflation uptick
* Equity markets close mixed ahead if Nvidia earnings
FX: USD fell modestly for a third straight day and below the year-to-date high at 106.51. Geopolitical tensions around the Ukraine-Russia lent a bid to the buck. But gains faded through the session. The US 10-year Treasury yield has fallen back to the pre-US election level.
EUR dipped below 1.0540 before closing virtually flat on the day just below 1.06. Final Eurozone CPI for October was confirmed at 0.3% M/M and 2.0% in the year. Core was also left unchanged at 2.7% Y/Y. The ECB’s Panetta said the ECB should move to a neutral or expansionary stance. However, this appears to be an out-of-consensus view.
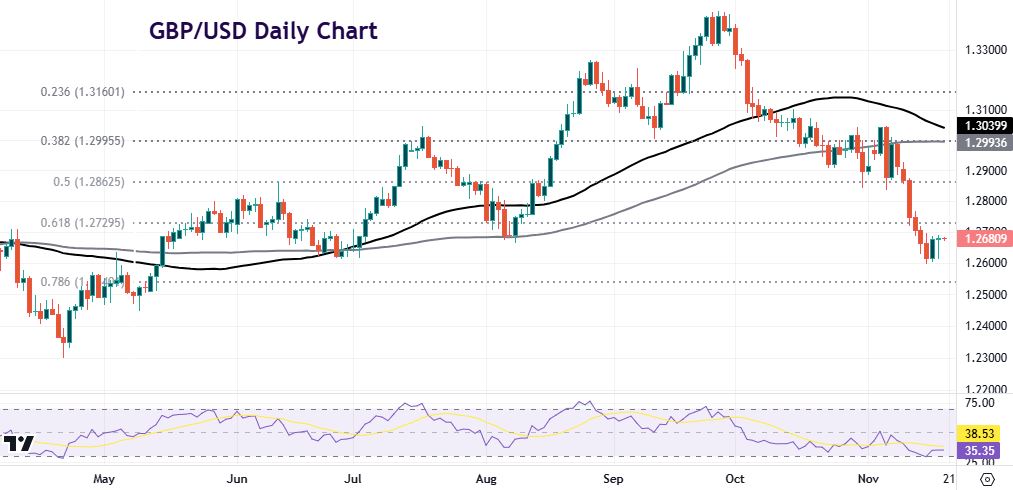
GBP fell near to recent lows before rebounding closer to 1.27. Governor Bailey was relatively cautious stating that the UK government’s recently announced increase in employer National Insurance contributions could result in higher prices, lower employment or other outcomes. The Governor said the BoE will have to move cautiously on policy as it monitors these impacts.
USD/JPY closed virtually unchanged on the day. The yen was generally better supported on the day among G10 currencies. There was also added support of warnings from the Japanese MoF that the authorities will act “appropriately” against excessive moves.
AUD ticked up for a third straight day. USD/CAD fell back to the August spike high at 1.3946. CPI was stronger than expected across the board. The 35bps of easing priced in for next month’s BoC meeting before the data was reined in.
US Stocks were mixed again with tech leading the gains. The S&P 500 settled 0.40% higher at 5,917. The tech-heavy Nasdaq 100 gained 0.71% to finish at 20,684. The Dow finished down 0.28% at 43,268. Nvidia rose 4.9% ahead of its results released after the closing bell tomorrow. The options market prices an -/+8.8% move in the giant chipmakers share price on the day of earnings, in line with the average (absolute) move seen on earnings over the past eight quarters.
The stock is seen as a bellwether for the AI mania that has boosted stocks this year. Nvidia’s shares are up nearly 200% this year, a gain that saw it overtake Apple as the world’s most valuable company in October.
Asian stocks: Futures are mixed. Asian equities were modestly green with little major newsflow affecting stocks. The ASX 200 outperformed with a fresh all-time top. Gold and tech shined. The Nikkei 225 was positive as the stronger yen didn’t acts a headwind. The Hang Seng and Shanghai Composite were choppy with gains and losses during the session. Stronger-than-expected Xiaomi failed to lift the stock.
Gold moved higher for a second straight day with the 100-day SMA in sight at $2655. The mixed risk mood helped haven demand.
Day Ahead – UK inflation
Consensus sees headline UK CPI ticking up to 2.2%, which would still be 0.4% below the last MPC forecast. That is primarily due to Ofgem’s 10% hike to the energy utility price cap, combined with last October’s utility price cut dropping out of the inflation calculation. The prior 1.7% print was below target for the first time since April. The core figure is seen moderating slightly to 3.1% from 3.2%.
The all-important metric which the MPC watch closely is services inflation. This is seen around 5%, after it slowed to 4.9% from 5.6% previously. That would match the MPC’s November MPR forecast. Wage growth remains relatively sticky, which is concerning some more hawkish officials at the Bank of England.
Chart of the Day – GBP tries to rebound
Regarding the BoE, the data release will need to surprise to the downside by some degree to bring a December cut back into contention. A sticky report would further pare expectations for a move. Markets currently price in less than a 20% chance of a 25bps cut in December. We note that November’s CPI will be published in the session before the BoE rate announcement in mid-December.
Decent support sits around 1.26 holding recent lows. Above is a Fib level (61.8%) of the April to September move at 1.2729. the next retracement level below is at 1.2539.
Disclaimer: The material provided here has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. Whilst it is not subject to any prohibition on dealing ahead of the dissemination of investment research we will not seek to take any advantage before providing it to our client. No representation or warranty is given as to the accuracy or completeness of this information and therefore it shouldn’t be relied upon as such. Any research provided does not have regard to specific financial situations, needs or investment objectives. Vantage accepts no responsibility for any use that may be made of these comments and for any consequences that result. Consequently, any person acting on it does so entirely at their own risk. We advise any readers of this material to seek professional advice where necessary. Without the approval of Vantage, reproduction or redistribution of this information isn’t permitted.
-
Open Trading Account
Discover the endless trading possibilities with our cutting-edge platform, designed to empower our traders. Practice trading the markets with a free demo account today.
-
Download Vantage App
Trade on the go with the Vantage All-In-One Trading App, where smooth execution and market access come together in the palm of your hand.
-
Start Trading
Are you an existing user? Login to your account to start trading 1,000+ CFD products including forex, indices, gold, shares and more.