Register
 Login
 Register




Alphabet Earnings Preview: Strong Fundamentals, But Market’s Still Not Buying In

Hebe Chen >
Senior Market Analyst
Hebe Chen >
Senior Market Analyst
 Updated Wed, 2025 July 23 06:36
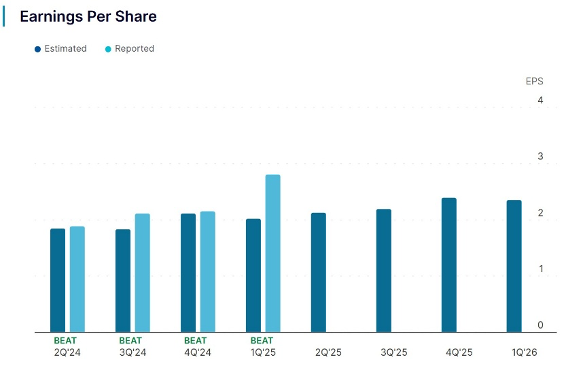
Alphabet is expected to report its Q2 earnings results on July 24 after US markets close.
Google’s parent company’s revenue is projected around $93.7 billion (+10–11% YoY), and EPS is expected to climb to $2.10–2.15, up roughly 12% from a year ago.
Yet despite these numbers and its deepening AI push, Alphabet shares are still down around 6% YTD—vastly underperforming its Mag 7 peers.
| Share price YTD | P/E | |
| Alphabet | -3.01% | 20.59 x |
| Amazon | +0.83% | 36.40x |
| Apple | -15.63% | 32.80x |
| Meta | +18.94% | 27.36 x |
| Microsoft | +20.25% | 39.07x |
That disconnect raises the question: will this quarter finally put Alphabet back on investor radars?
Key Focus Areas:
AI Investment Returns & Search Impact: Google’s rollout of Gemini 2.5 Pro to 1.5 billion Search users marks a significant AI advancement—but with billions invested in infrastructure, investors now demand tangible returns. The critical question: is AI enhancing ad monetization or cannibalizing it?
If Gemini drives higher engagement and ad yield, it justifies the expenditure. If it reduces search queries and clicks, it risks compromising Google’s primary revenue engine. This quarter offers an early read on whether AI is fueling Google’s profit engine—or disrupting it with uncertain returns.
Google Cloud Performance: Cloud remains a bright spot: Q1 saw approximately 28% cloud revenue growth; Q2 is expected around 26% year-over-year. Further margin expansion may help cushion rising AI infrastructure costs.
Margin Discipline: Operating margin last quarter reached 34.1%—a multi-year peak. The challenge is whether Alphabet can sustain this discipline while deploying substantial capital toward AI infrastructure.
Regulatory Pressure: A US court ruling declared Google monopolistic in search advertising. Although no remedies have been implemented, potential scenarios like Chrome divestiture could significantly impact valuations.
Despite moderating growth momentum, Alphabet’s fundamental business remains solid—yet the stock has notably failed to capture the AI enthusiasm driving peers. The upcoming earnings must demonstrate more than robust financials; they need to prove Alphabet’s AI and Cloud investments are generating defensible, scalable returns without compromising existing product strength.
If management delivers on this front, investor attention—and capital flows—could rapidly return, particularly given the stock’s reasonable 20x forward EPS valuation for a company of this innovative capacity and leading position.
Alphabet Share Price Technical Analysis
Alphabet (GOOGL) edged up to $191.34 ahead of earnings, sitting right below key resistance at $192–$194. This zone has capped gains since January, with the stock fading from it after each earnings in the past three quarters.
Technically, price remains in a rising channel, with the short-term bias still skewed higher as long as it holds above $178. However, the overbought KDJ indicator (above 100) flags exhaustion risk.
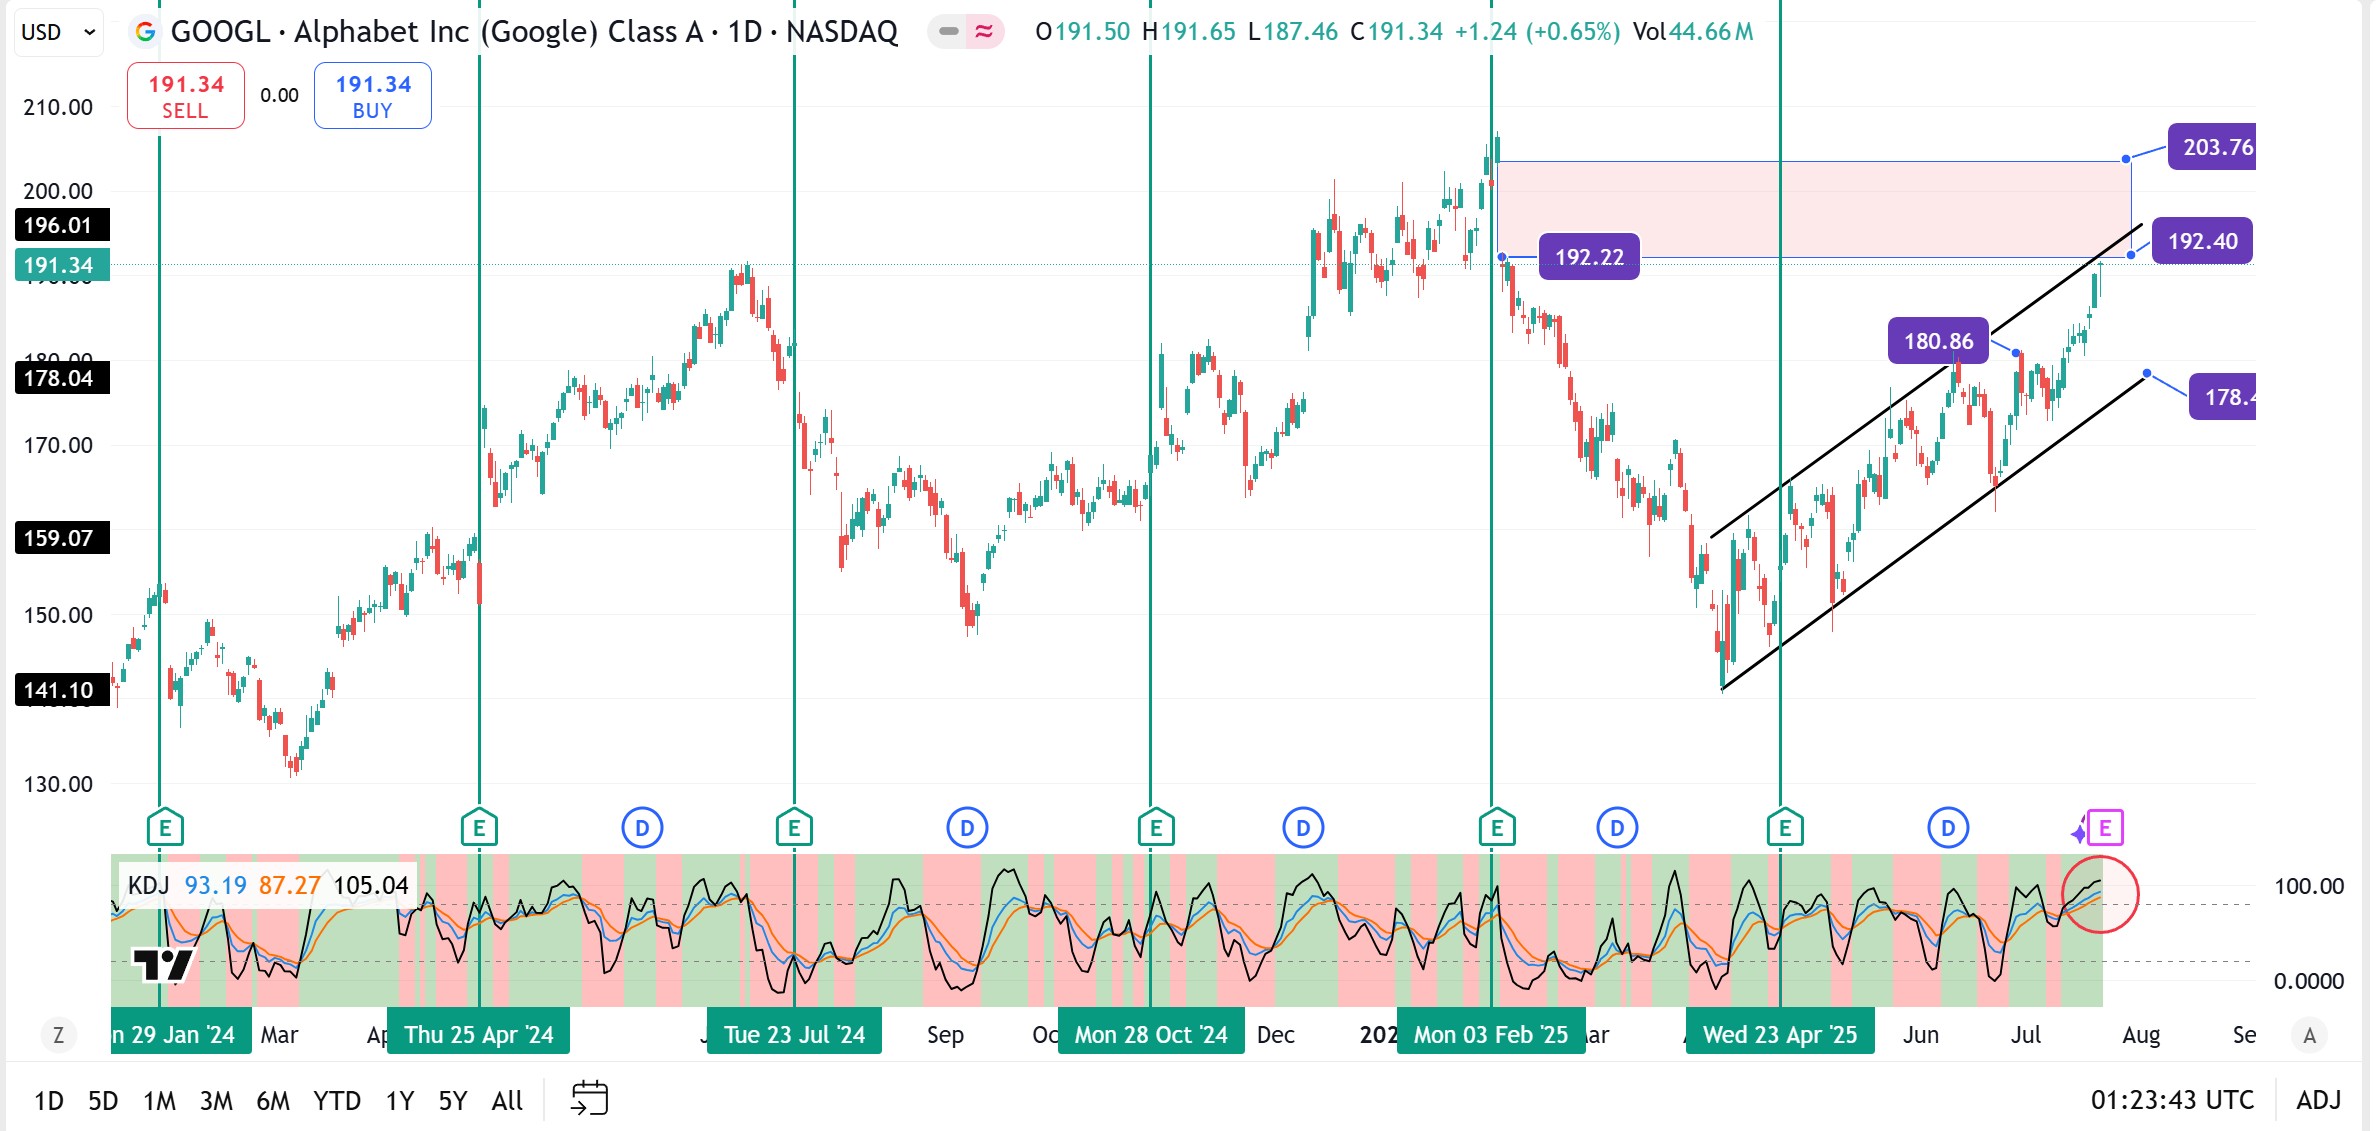
For the past four quarters, GOOGL’s post-earnings price action has been mixed—rallying twice out of the past four quarters. The current setup suggests any miss or lukewarm guidance could spark a pullback toward $180. Conversely, a strong beat could finally trigger a clean breakout, with the potential to fill the price gap between $192-$203.
Overall, the path forward hinges primarily on whether Alphabet can convert strong AI investment and advertising momentum into real monetisation gains. Traders should watch $192.40 closely—rejection here may bring a tactical reversal.
Disclaimer: The material provided here has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. Whilst it is not subject to any prohibition on dealing ahead of the dissemination of investment research we will not seek to take any advantage before providing it to our client. No representation or warranty is given as to the accuracy or completeness of this information and therefore it shouldn’t be relied upon as such. Any research provided does not have regard to specific financial situations, needs or investment objectives. Vantage accepts no responsibility for any use that may be made of these comments and for any consequences that result. Consequently, any person acting on it does so entirely at their own risk. We advise any readers of this material to seek professional advice where necessary. Without the approval of Vantage, reproduction or redistribution of this information isn’t permitted.
-
Open Trading Account
Discover the endless trading possibilities with our cutting-edge platform, designed to empower our traders. Practice trading the markets with a free demo account today.
-
Download Vantage App
Trade on the go with the Vantage All-In-One Trading App, where smooth execution and market access come together in the palm of your hand.
-
Start Trading
Are you an existing user? Login to your account to start trading 1,000+ CFD products including forex, indices, gold, shares and more.