-

-


Download App
-


-

-

-
Search query too short. Please enter a full word or phrase.
-

Keywords
- Forex Trading
- Vantage Rewards
- Trading Fees
Popular Search
- Trading Accounts
- MT4
- MT5
- TradingView
- Promotions




Tech fuels stock gains as Bitcoin excitement soars
Jamie Dutta >
9 January 2024 | Daily Analysis | 5 min read
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
Headlines
* Strong boost from chips sees Nasdaq lead equity gains
* Dollar’s best start in decades falters before key CPI data
* US inflation expectations decline across all horizons in NY Fed Survey
* Bitcoin surges to $47,000as ETF excitement may bring huge inflows
FX: USD is trading off risk sentiment as much as anything to kick off the year. That has been weak as markets modestly re-assess the aggressive rate cuts that were heavily priced in late last year. A plunge in inflation expectations also grabbed the headlines. The equity bid saw dollar selling and yields drop. Eyes are on Thursday’s CPI data and more Fed speakers. After last week’s mixed NFP, it seems the market is more focused on worse than expected data than any upside surprises. We note the prices paid ISM Manufacturing component hit a six-month low last Wednesday.
EUR is stuck within a range roughly between 1.0882 and 1.0980. These are two Fib levels of the December rally. The midpoint is at 1.0931. Monday saw mixed data with weaker Factory Orders and better trade figures. Confidence figures showed modest improvements.
GBP rose for a fourth straight day. But cable has been stuck in a range between 1.26 and 1.28 since mid-December. The high touched 1.2828 which was last seen in August 2023. Bailey speaks on Wednesday and may push back against rate cut talk.
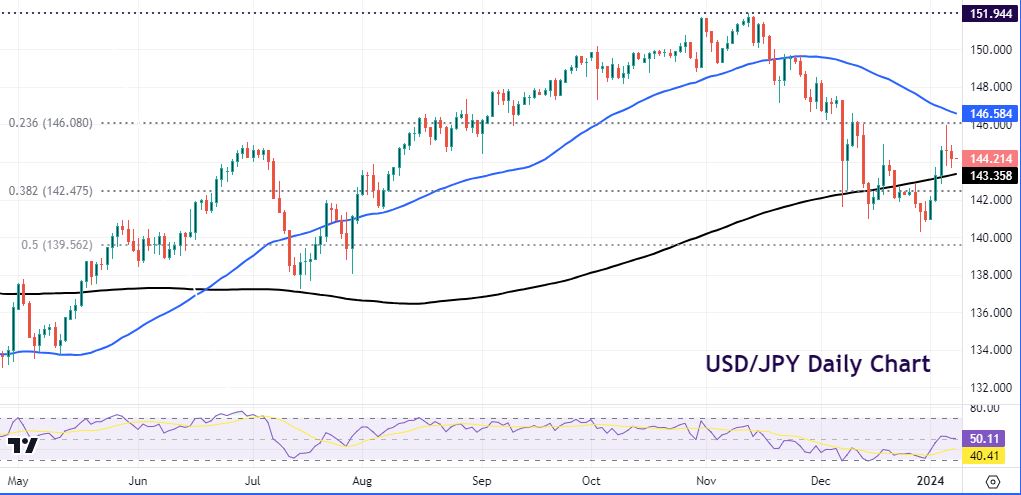
USD/JPY fell after spiking up to 145.97 on Friday immediately after the US employment report. The 200-day SMA sits at 143.29. Tokyo CPI data is released shortly.
AUD sunk to a three-week low on the NFP numbers. But the rebound after the ISM Services data saw the aussie finish very mildly higher on the day. Eyes are on the CPI figures out Wednesday. USD/CAD tried to move higher but found resistance again around 1.34. There were softer than expected headline job numbers on Friday. But the jump in wages should stop any early BoC rate cuts. There are around 9bps priced into the March meeting.
Stocks: US equities rose strongly putting paid to the idea of “how the first five days of the year go, so goes the year”. The S&P 500 added 1.41% to settle at 4,763. That was it biggest one-day percentage gain since mid-November. The tech-heavy Nasdaq 100 finished 2.11% higher at 16,649. The Dow lagged due to sellers in Boeing, but the index settled up 0.58% at 37,683.Buying was led by semiconductor stocks with Nvidia up 6.43%. This came after the giant chip maker revealed processors and software for AI computing at a consumer electronics show. Energy was the only losing sector as Saudi Arabia price cuts fuelled demand doubts. The Magnificent Seven soared higher erasing 75% of their losses for the year.
Asian futures are in the green. Stocks traded lower on Monday with a muted start to the week. Hong Kong and Shanghai were pressured amid banking woes and geopolitical frictions. Hong Kong selling was made worse by tech losses.
Gold initially sold off heavily in the European session showing losses of more than 1%. But dollar weakness amid softer Treasury yields saw gold claw back a small amount of losses. Eyes are on Thursday’s US inflation data.
Day Ahead – Tokyo CPI
It is widely hoped that the bank of Japan will normalise policy this year. But with policymakers giving no signals at its recent meeting that the era of ultra-loose policy conditions is nearing its end, this week’s Tokyo inflation data could spark volatility. The data for November revealed notable slowdowns in both headline and core consumer prices. The latter rate hit 2.3% y/y, slightly above the Bank’s objective of 2%.
Further easing could point to a similar reaction in the national CPI data for the month. That might underpin support that Japanese policymakers will not be in a rush to take interest rates out of negative territory. That would potentially further hurt the recently wounded yen.
Chart of the Day – USD/JPY resuming downtrend?
The major has dropped sharply from highs near 152 in November. A low was made late last month at 140.24 from which US Treasury yields have bounced. That gave a lift to the pair to which it is highly correlated. The initial Fib level of the 2023 rally is at 146.08. A major Fib level (38.2%) sits at 142.47, just below the 200-day SMA at 143.29.
As we said in the above section, there is much hope that the BOJ will finally exit its uber-dovish policy settings in 2024. Any market-led turn lower in US rates again would certainly help the BoJ without JGB yields surging.


- [DAILY TRADING] UKOUSD & USOUSD Analysis 21 August 2026 — Brent Crude Oil Price Holds Near $94 as WTI Steadies
- [DAILY TRADING] Alibaba 21 August 2026 – BABA Stock Price Rebounds to $130.57 After Earnings Miss
- [DAILY TRADING]: EUR/USD Analysis 21 August 2026 — EUR/USD Holds 1.1697, Near 3-Month High, ECB Hike Bets Firm
- [DAILY TRADING] Oracle Stock 21 August 2026 – ORCL Holds $142 as Pipeline Delay Meets Debt Fears
- [DAILY TRADING] Nasdaq 100 21 August 2026 – Climbs Back to 29,347 as Wall Street Waits on Jackson Hole
- [DAILY TRADING] AUD/USD Analysis 21 August 2026 — AUD/USD Hits 0.7150 as Dollar Slides, Aussie Jobs Miss
- Yields jump, stock slide after Bessent intervention fails
- [DAILY TRADING] Lowe’s 20 Aug 2026 – LOW Rises as Q2 EPS Beats, Guidance Cut to Range Floor