-

-


Download App
-


-

-

-
Search query too short. Please enter a full word or phrase.
-

Keywords
Popular Search




Tech earnings and inline CPI boosts stocks
- President Trump claims US has ‘total control’ over Hormuz as Iran harden stance
- Latest US inflation figures give Fed officials breathing room
- Dollar is little changed as in-line CPI tempers rate hike bets
- Potential ‘peak earnings’ set the stage for disappointing stocks
USD found a bid late on as the Dollar Index continued to trade around the 100-day SMA at 99.74. Support sits at 99.41 with resistance at the top of the current range just above 100. CPI printed inline in the major metrics with headline at 0.1% m/m and 3.4% y/y, and core at 0.2% and 2.5%. Anything below 2.5% would have been the lowest since early April 2021. September rate hike odds moved lower, from 49% to 40% as the 10-year Treasury yield slid further away from strong resistance at 4.74% though it did retrace this move through the US session. That’s now three months of core m/m at or below 0.2%, which is needed over several months to bring CPI back to the Fed’s 2% target.
EUR continued to consolidate in the mid-1.15s, with last week’s high at 1.1580, a near 10-week peak that needs to be beaten to see 1.16 and above. The 200-day SMA still resides at 1.1626. Rangebound trading is the name of the game, even after a big risk event like US CPI. The inline report hasn’t helped FX volatility and we may need to get to September and post-summer to see more interesting price action. Fundamentals remain supportive for what it’s worth, with two-year yield spreads marginally higher.
GBP slid late on after cable got close to the mid-July high around 1.3557. Next upside target for bulls is then the May top at 1.3657. Bullish momentum has been solid with eyes on Q2 GDP data released today.
JPY hit the long-term upward trendline from the April 2025 low around 159.30 and turned lower before then closing pretty much on it. There was an Asian trade spike move before prices moved near to that low through the day and after benign US inflation figures. Media reports are highlighting tension between US and Japanese officials as the US pushes for BoJ rate hikes as part of the intervention deal.
US stocks: The S&P 500 added 0.26% to close at 7,748, the Nasdaq closed up 0.74% at 29,743 and the Dow Jones settled lower by 0.04% at 5`3,775. Only three sectors were negative with Consumer Discretionary, Materials and Communication Services in the red. Real Estate and Tech were the biggest outperformers. CoreWeave, the AI cloud infrastructure provider, reported Tuesday night and the stock jumped 19%. Shares had fallen after each of the company’s first five reports as a public company, but increasing customer commitments saw investors overlook losses and debt, with the outlook raised. Nebius soared 34% as AI revenue jumped and the company potentially transitioned from a massive backlog to explosive cash flow. Lumentum ripped 13.6% higher as AI demand fuelled a ‘transformational’ quarter. Super Micro surged 19% on upbeat annual revenue eon data centre adoption and a stunning outlook
Asian Stocks: Futures are mixed. APAC stocks were mixed on uncertain US-Iran tension as markets awaited US CPI. The ASX 200 sold off with financials focused on CBA results which modestly beat estimates but a warning from the CEO about slowing economic growth. The Nikkei 225 was choppy after its holiday with eyes on yen intervention and BoJ rate hike chatter. The Hang Seng and Shanghai Comp were mixed with Hong Kong watching big earnings reports like Ten Cent who kicked off tech earnings in China.
Gold pushed higher as it briefly made a fresh 7-week cycle high at $4,428. Benign inflation data saw bug’s nerves soothed, with eyes on the 200-day SMA at $4,485. Initial support sits around $4,334. September rate hike odds moved lower after the CPI release nearer to 40%.
Day Ahead – UK Q2 GDP, US PPI
Expectations are for UK second quarter growth to come in at 0.4% q/q versus 0.6% previously, and 1.1% y/y. The UK topped the G7 table in the first three months of 2026. Early year seasonal momentum should be sustained, boosted by retail sales due to the World Cup and hot weather. But the wider picture is likely less convincing, with business survey indicators pointing to weaker services activity and appearing less solid than GDP data. Investment uncertainty around the Middle East conflict also lingers.
US PPI shows pipeline price pressures and along with CPI figures, feeds into the Fed’s favoured inflation gauge, core PCE data released at the end of the month. Both headline and core PPI are forecast to ease, to 4.9% from 5.5% and 4.2% from 4.7% respectively. Base effects are likely a big reason for the decline. The monthly headline should print around 0.2%, up from the 0.3% contraction seen in June, with core m/m at rising one-tenth to 0.3%. Economists note that relatively stable petroleum product prices through July are expected to help keep overall headline wholesale inflation contained.
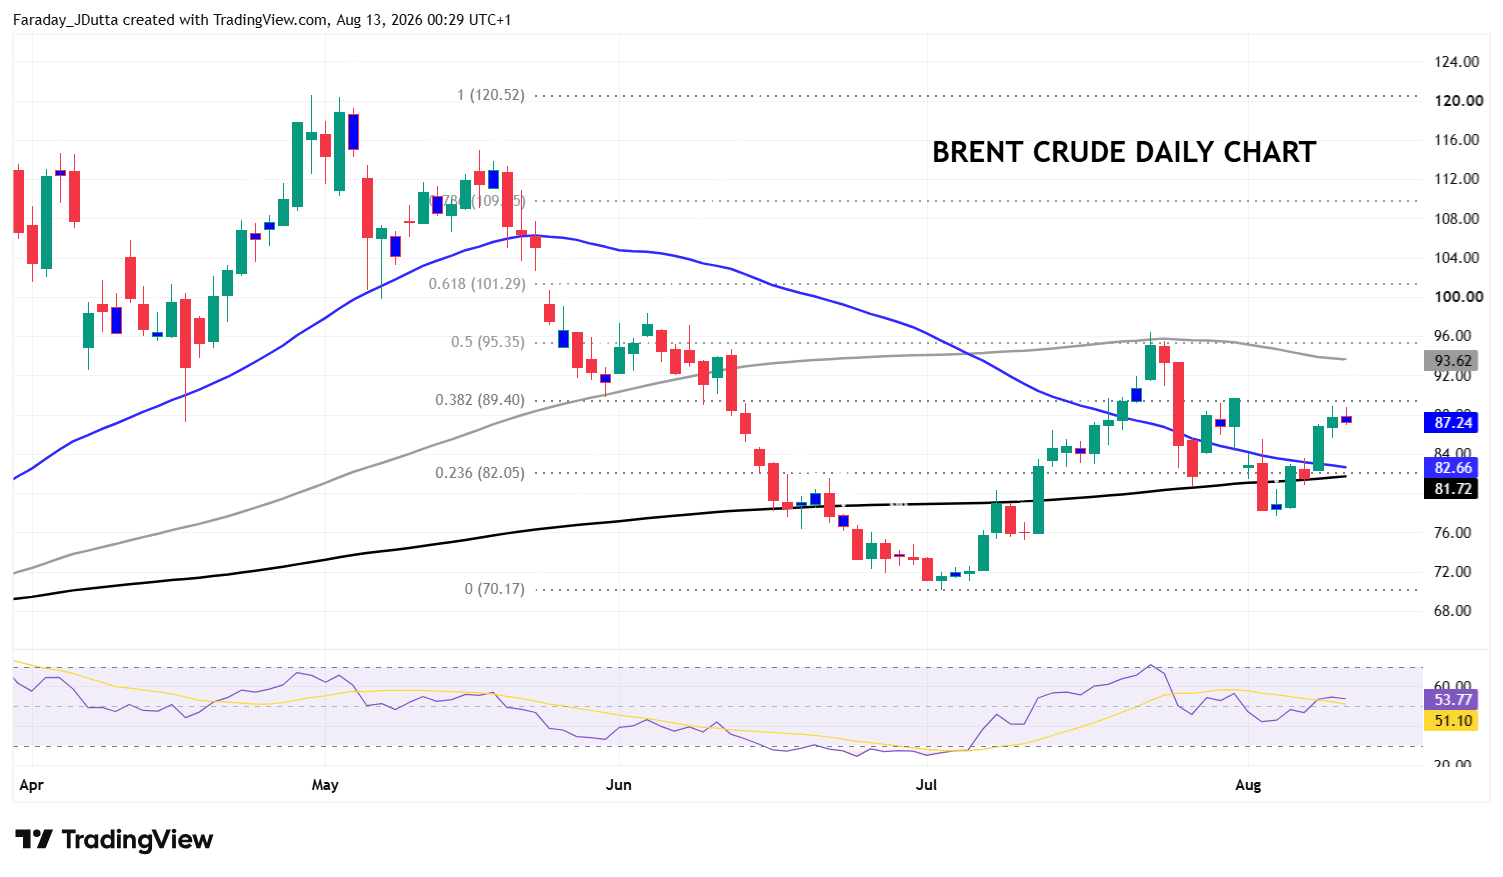
Chart of the Day – Brent crude awaiting big catalyst
We said in the weekly that the broader market has been clearly saying that US rate expectations had been driven far more by data and Fed communication than by energy prices. Indeed, you’d think even oil markets would be largely immune to headlines about a US–Iran deal. But a pattern keeps repeating – initial enthusiasm when negotiations appear promising, only for that optimism to dissolve just as quickly. So, the oil market remains very headline-driven, which leaves prices whipsawing. We have steered clear of many of the headlines during this daily, simply as they are changing so often.
That means studying technicals and charts can help steer us. After dipping to $70.17 in early July, prices bounced to the midpoint of the late April high to July low move at $95.35 and the 100-day SMA, now at $93.63. A sell-off saw the 200-day SMA pierced briefly, which is now at $81.72. We are now just below the major Fib level (38.2%) at $89.40.


- # Asian Markets News Today
- # Crude Oil News Today
- # Earnings News Today
- # Economic News Today
- # Featured News
- # Federal Reserve News
- # Commodity Market News
- # Interest Rate News
- # Financial News
- # Forex News Today
- # Gold News Today
- # Market News Today
- Yields jump, stock slide after Bessent intervention fails
- Dollar, yields sink as US Treasury to intervene in bond markets
- Tech drags as rising bond yields cause wider concerns
- Mild risk-off as Middle East escalation worries rise
- Week Ahead: US Yields and UK Data in Focus
- Tech pushes S&P 500 to record as Treasury yields pressured by soft PPI
- Eyes on US CPI as FX volatility plunges
- Crude and yields jump, hindering stock’s record rally